All Categories
Featured
A Complete Guide to 2026 Relief
The online path is eHome's eight-hour course. It costs $100 and is the only online choice the firm accepts. Structures and HomeView are particularly rejected, since they do not have the one-hour, individually counseling follow-up. The in-person or virtual course goes through NeighborWorks America or any HUD-approved therapy firm, with charges that differ by service provider.
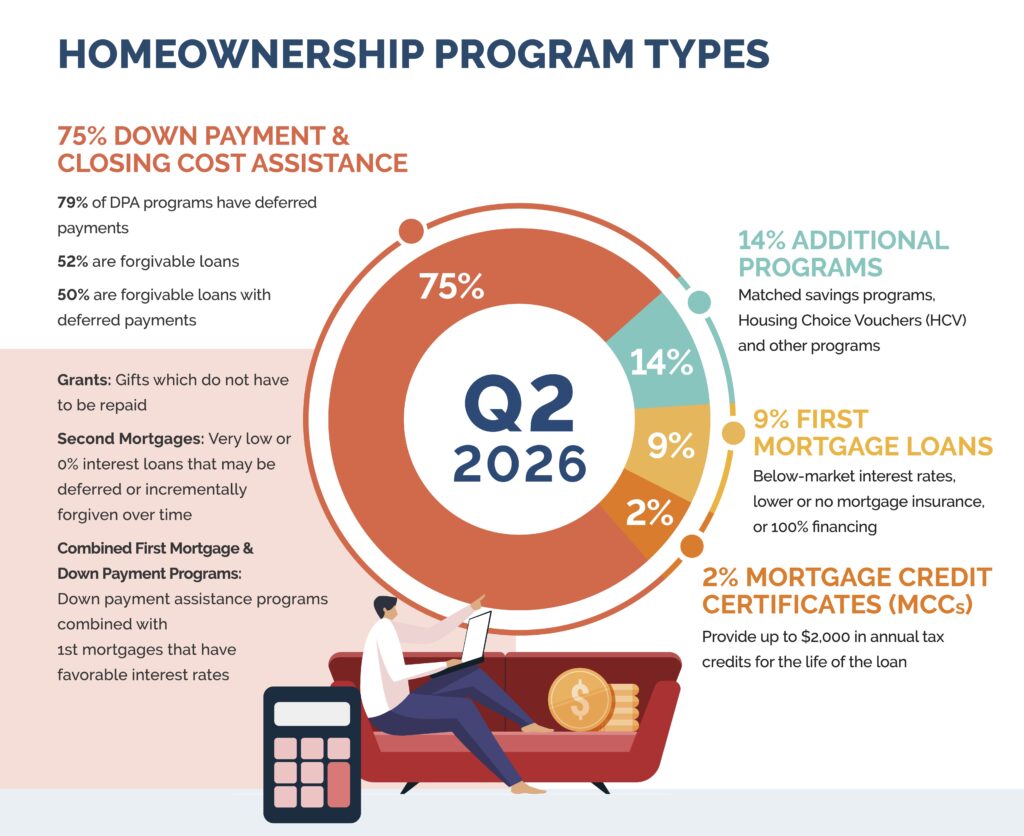
The requirement earns its keep. The curriculum covers budgeting for taxes and insurance coverage, how escrow works, and what maintenance in fact costs. Repeat buyers utilizing a standalone very first home loan avoid it entirely. The pairings are rule-bound, so think about repaired menus instead of a buffet. The first menu is a CalPLUS very first home mortgage with MyHome in second position and ZIP in third, covering deposit and closing costs in one closing.
It is a standard CalHFA first with MyHome alone, which leaves room under the 105% combined loan-to-value cap for outside layers. Many city and county programs layer on top of the state package, including San Diego and Los Angeles programs with their own deferred loans.
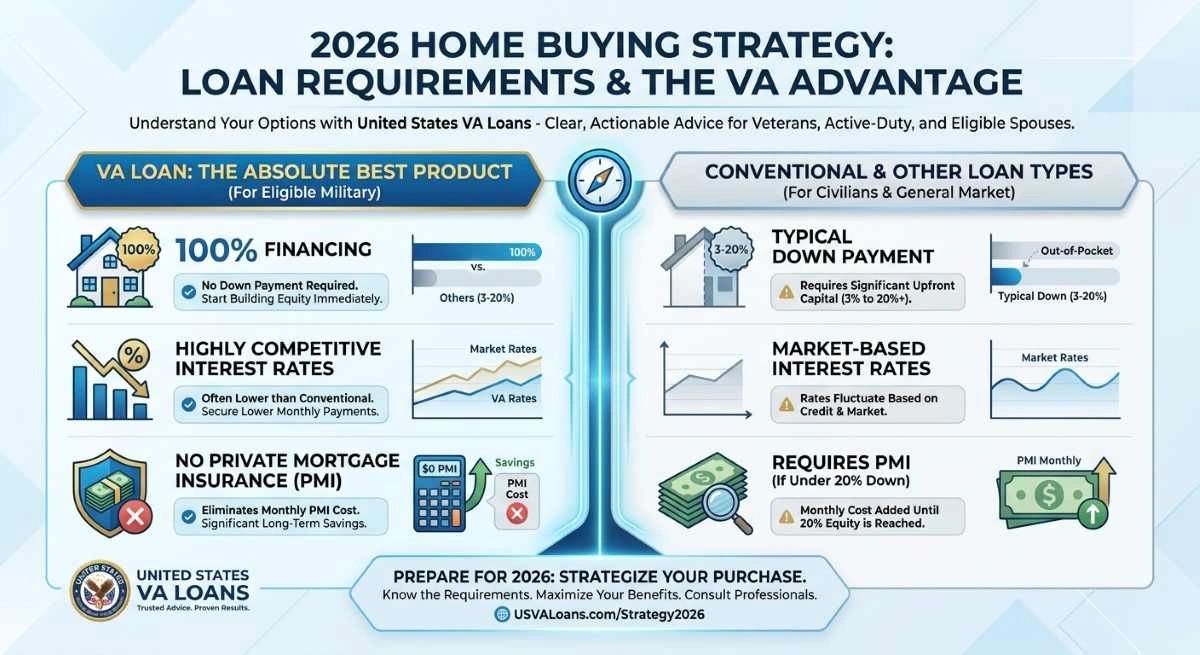
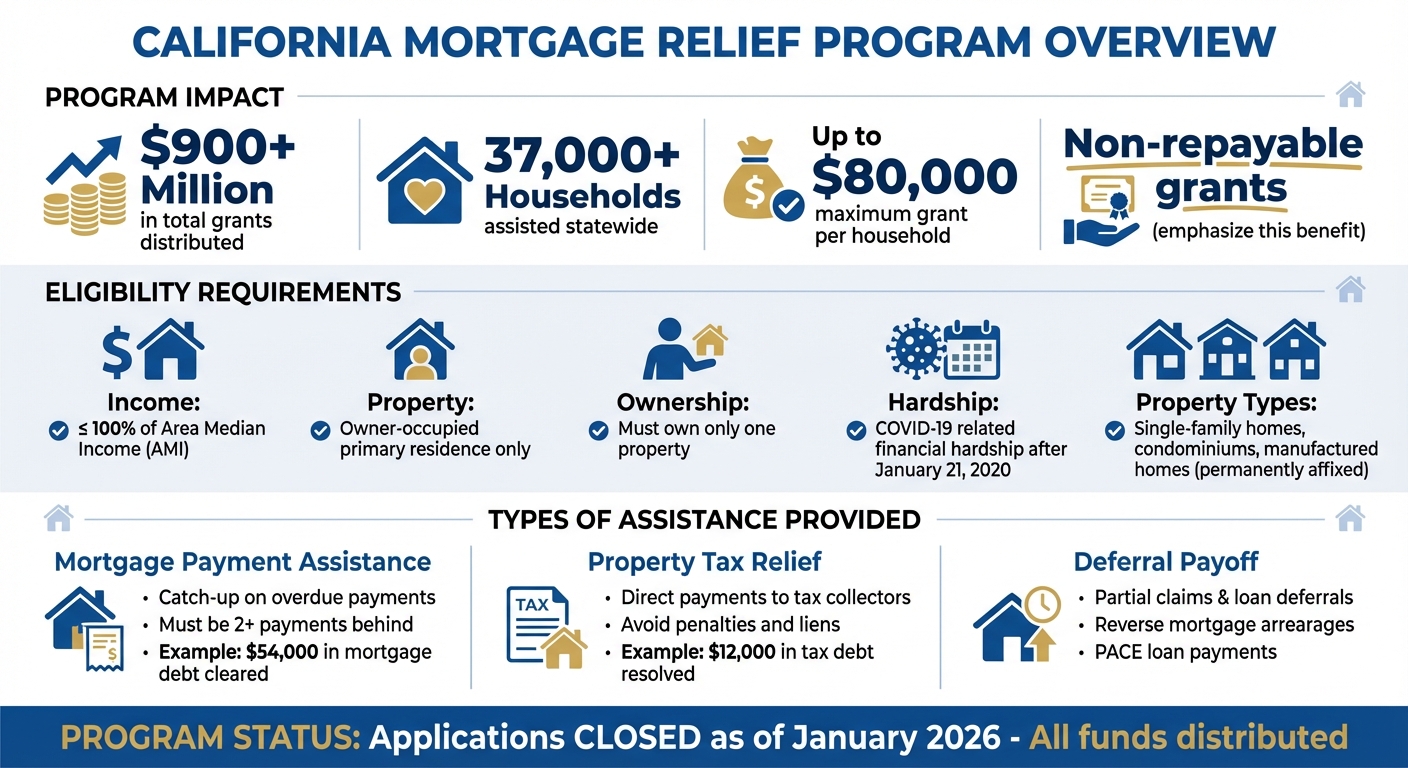
One sincere care: the state's support programs are repayable loans, not grants. Buyers hunting for cash that never has actually to be repaid are truly shopping for lender grants or forgivable regional programs, which is a various classification we compare listed below.
Key Methods to Get Mortgage Relief in 2026Ways to Manage Loan Debt Effectively Now
Those with thinner scores lean on the FHA menu's 640 floor. Veterans can connect MyHome to a VA loan in California, stacking state closing cost aid onto a zero-down federal advantage. That one is silently excellent. Talk to a real individual Rod has actually arranged California mortgages for more than 40 years and understands which state pairings in fact reach the closing table.
There is no separate state application to submit. Your loan officer reserves the programs while underwriting the first mortgage. The documents mirrors any purchase loan. Anticipate income tax return, pay stubs, bank declarations, and employment confirmation. Support loans are approved alongside the very first mortgage, not in series. That keeps things fast.
Navigating New Mortgage Relief Programs in 2026
And novice buyer purchases of resale homes need an one-year home warranty under the present matrices. Pre-approval through a getting involved loan provider doubles as program qualification, which lets your offer stand on verified numbers.

Latest Posts
Refinance Advice to Reduce Payments in 2026

The Essential Guide to 2026 Home Loan Assistance
Benefits of Early Mortgage Relief in 2026