All Categories
Featured

Exploring Mortgage Refinancing Help Today
Modernization of Home Home Loan Disclosure Act (HMDA) Data Collection and Disclosure. (a) The CFPB shall consider, as appropriate and consistent with relevant law, proposing modifications to Regulation C to raise the asset limit for exemption from HMDA data collection and reporting requirements for smaller banks, to exclude questions from the scope of HMDA, and to guarantee that disclosures protect personal privacy and minimize concerns, including insufficiently tailored, costly, and complex software and training needed for reporting monetary organizations.
- Capital and Liquidity Positioning. (a) The Vice Chairman for Guidance of the Federal Reserve, the Chairman of the NCUA Board, the Chairperson of the Board of Directors of the FDIC, the Comptroller of the Currency, and the Director of the Federal Real Estate Financing Firm (FHFA) will think about, as proper and constant with appropriate law: (i) modifying capital policies, constant with proper risk-management requirements, to customize threat weights for all banks, consisting of community banks and other smaller sized banks, for portfolio mortgages, maintenance rights, and warehouse credit lines to the material credit threat of the exposure; (ii) modernizing security valuation and transfer systems in between the Federal Reserve and Federal Home Loan Banks (FHLBs); (iii) expanding access to longerdated FHLB advances tied to domestic mortgage properties; (iv) developing targeted FHLB liquidity programs for entrylevel housing, owneroccupied purchase loans, and little residential contractors; (v) accelerating security boarding and appraisal procedures through standardized information and digital documents; and (vi) refocusing the FHLBs' Economical Real estate Program on faster-cycle execution and greater financial take advantage of for small and owner-occupied housing jobs.
(c) Within 120 days of the date of this order, the Director of the FHFA, in assessment with the heads of other pertinent executive departments and agencies, shall submit a report to the Assistant to the President for Economic Policy and the Director of the Office of Management and Budget on the performance of national real estate finance markets.
Strategic Mortgage Planning Tips for 2026Top State Assistance Programs to Help Homeowners
Sec. 5. Construction and Housing Supply. (a) The Vice Chairman for Supervision of the Federal Reserve, the Director of the CFPB, the Chairman of the NCUA Board, the Chairperson of the Board of Directors of the FDIC, and the Comptroller of the Currency, shall think about, as suitable and consistent with applicable law, modifying supervisory assistance both to leave out one-to four-family residential advancement and building financing from commercial genuine estate concentration assistance and to make sure supervisory expectations support accountable building and construction financing by neighborhood banks.
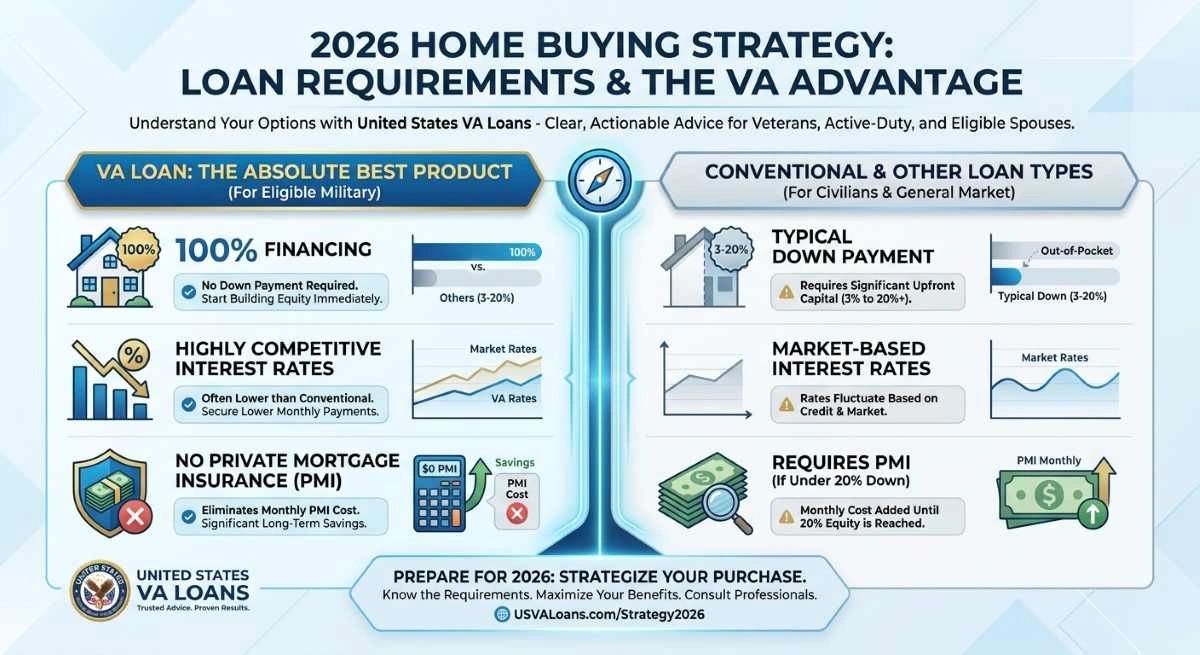
Critical Strategic Planning Tips for 2026- Appraisal Modernization. (a) The Vice Chairman for Guidance of the Federal Reserve, the Director of the CFPB, the Chairman of the NCUA Board, the Chairperson of Board of Directors of the FDIC, the Comptroller of the Currency, and the Director of the FHFA will think about, as proper and constant with suitable law and their statutory authorities: (i) updating appraisal policies and guidance to broaden using alternative evaluation designs, desktop and hybrid appraisals, and synthetic intelligence evaluation tools; (ii) simplifying appraiser qualification requirements; and (iii) minimizing appraisal requirements for low-risk transactions, including low loan-to-value refinancing and smallbalance loans; and setting clear appraisal timelines.
Digital Mortgage Modernization. (a) The Secretary of Farming, the Secretary of HUD, the Secretary of VA, and the Director of the FHFA shall think about, as appropriate and constant with suitable law: (i) removing unnecessary wetsignature requirements for disclosures, applications, closing files, and similar documents; (ii) standardizing acceptance of electronic signatures, e-notes, and remote online notarization; and (iii) promoting digital home mortgage requirements.
- Servicing and Supervisory Certainty. (a) The Secretary of HUD, the Vice Chairman for Guidance of the Federal Reserve, the Director of the CFPB, the Chairman of the NCUA Board, the Chairperson of the Board of Directors of the FDIC, and the Comptroller of the Currency will think about, as proper and constant with appropriate law: (i) lining up supervisory expectations to support portfolio mortgage maintenance as a core community banking function; extending curefirst requirements to goodfaith servicing mistakes; streamlining loss mitigation requirements; and issuing a proposed rule supplying exemptions from intricate home loan services for smaller sized banks; and (ii) ensuring that supervisory assessments of performing, prudently underwritten portfolio loans do not focus on technical problems or rely on progressing supervisory interpretations.
- Enforcement. (a) The Vice Chairman for Guidance of the Federal Reserve, the Director of the CFPB, the Chairman of the NCUA Board, the Chairperson of the Board of Directors of the FDIC, and the Comptroller of the Currency shall think about, as proper and consistent with suitable law, promulgating a policy versus enforcement actions for offenses of consumer monetary laws that: (i) dissuades imposing civil financial penalties, except where the underlying offenses are willful, knowing, or careless; (ii) thinks about great business conduct, consisting of a bank's correction of good-faith, technical compliance errors; and (iii) allows organizations a sensible chance for self-identification and remediation of appropriate compliance matters.

Latest Posts
Refinance Advice to Reduce Payments in 2026

The Essential Guide to 2026 Home Loan Assistance
Benefits of Early Mortgage Relief in 2026