All Categories
Featured
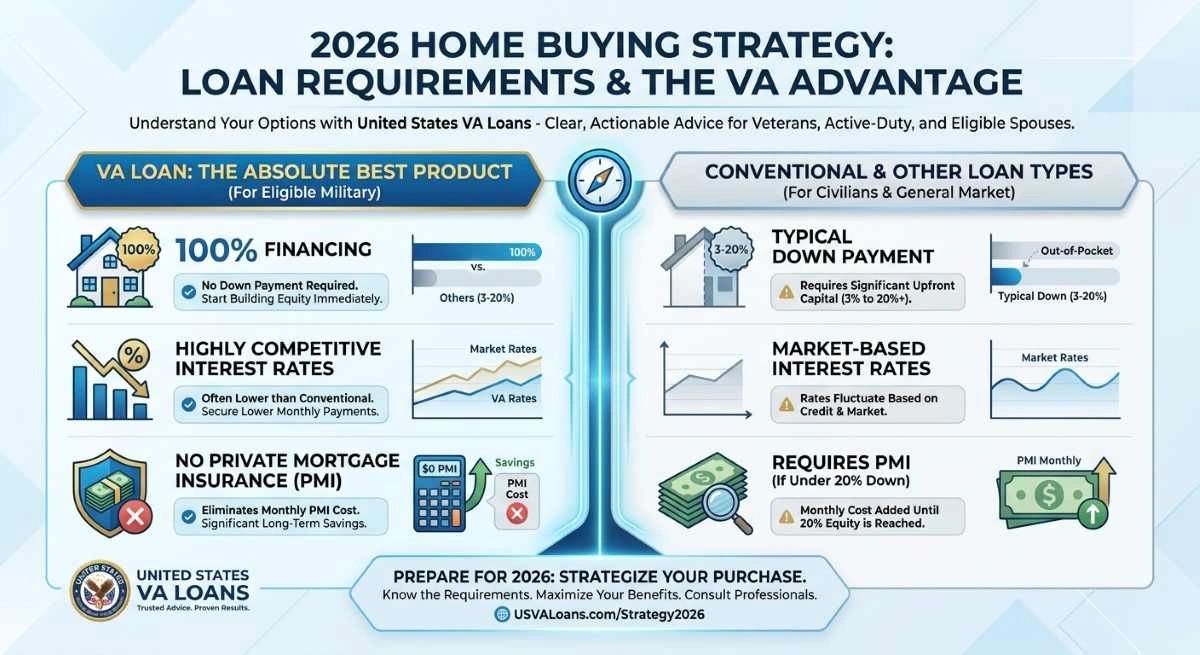

Strategic Advice for Managing Your Home Loan in 2026
Qualified borrowers with loan quantities less than or equivalent to $150,000 may get: 8% of the lower of the purchase price or appraised value with no maximum dollar limitation in downpayment and closing cost help. Keep in mind: This support quantity undergoes accessibility. Qualified customers with loan amounts higher than or equivalent to $150,001 may get: 5% of the lesser of the purchase rate or appraised value without any maximum dollar limitation in downpayment and closing expense help.
Payment of the K-DATE loan is delayed and ends up being due at the time of expiration. The time of expiration takes place upon the sale of the home, re-finance of the home mortgage or the benefit of the first home mortgage. The Keystone Due Sometimes of Expiration Loan Program (K-DATE) can be used in conjunction with the following PHFA first mortgage home purchase loan programs: Buyers should meet the requirements of the appropriate PHFA very first mortgage program, and should likewise fulfill the requirements related to the Keystone Due Sometimes of Expiration Loan Program (K-DATE) which are listed below: All borrowers must have a minimum credit report of 660.
Help can just be used for the minimum required downpayment and/or closing costs. The minimum loan quantity is $500. The K-DATE Loan Program might not be integrated with any other PHFA help program, other than for the Gain Access To Home Adjustment Loan Program. The K-DATE Loan Program may be utilized on Traditional, FHA, VA or RD loans.
Navigating Refinancing Options to Lower Payments in 2026
The asset constraint of liquid funds may not be greater than $50,000 after subtracting the funds required to close on the loan. This includes money and funds in monitoring and savings accounts, stocks, bonds, certificates of deposit and similar liquid accounts. Funds from retirement accounts such as 401(k)s, IRAs and pension funds will only be thought about if they can be withdrawn without a charge due to the borrower conference age requirements and/or being retired.
All programs provide a set rates of interest for 30 years. The Keystone Home mortgage program has income and purchase cost limitations, in addition to a first time homebuyer requirement particular to each county. The HFA Preferred(Lo MI) loan has earnings limits but does not have very first time homebuyer requirements, nor does it have purchase rate limits.
Buyers with an impairment or a handicapped family member, who are qualified for any of these mortgage programs, may also be qualified to get funds to make accessibility adjustments to the home they buy and may likewise be eligible for up to $15,000 in a no interest downpayment and closing cost assistance loan through the Gain access to Downpayment and Closing Expense Assistance Program.
Time buyers may likewise be eligible for up to $10,000 in a no interest downpayment and closing cost assistance loan through the HOMEstead Program. This support might be utilized with or without the adjustment program, but the property should fulfill HUDs Housing Quality Standards, and there are maximum earnings and purchase rate limitations depending upon the county in which the home lies.
Stop Foreclosure in 2026
You might be able to find a home that matches your way of life and living requirements simply the way it is. It provides a zero-interest loan between $1,000 and $10,000 in conjunction with a PHFA Keystone Home Loan or Keystone Government Loan.
How to Successfully Avoid Foreclosure in 2026Before you sign a sales agreement with the seller, you ought to initially determine if your home suits your present and future living requirements, or if it could be made suitable with up to $10,000 in adjustments. An expert home designer can help you decide what kind of modifications should be made.
If you will be making adjustments to the home, you will require to offer the lender with an agreement for the modifications. The contract must: Be signed by you and a professional signed up with the PA Attorney general of the United States's workplace; Rest upon approval of your mortgage; State the particular work to be done and need to be supported by specs, plans, drawings, etc; Consist of the real maximum quantity that can be charged (not approximated amount); Include a release of lien clause to maintain clear title; State that the professional agrees to complete the work in compliance with all suitable building codes and zoning limitations and to obtain the required authorizations and a certificate of completion within 90 days of your closing date.
Simply put, the home's value does not need to support the quantity of the modifications. The funds for the modification(s) will be held in escrow when you close on your home. A preliminary payment in a quantity up to 1/3 of the agreement quantity may be disbursed to the contractor at or after your closing date.

Latest Posts
Refinance Advice to Reduce Payments in 2026

The Essential Guide to 2026 Home Loan Assistance
Benefits of Early Mortgage Relief in 2026