All Categories
Featured
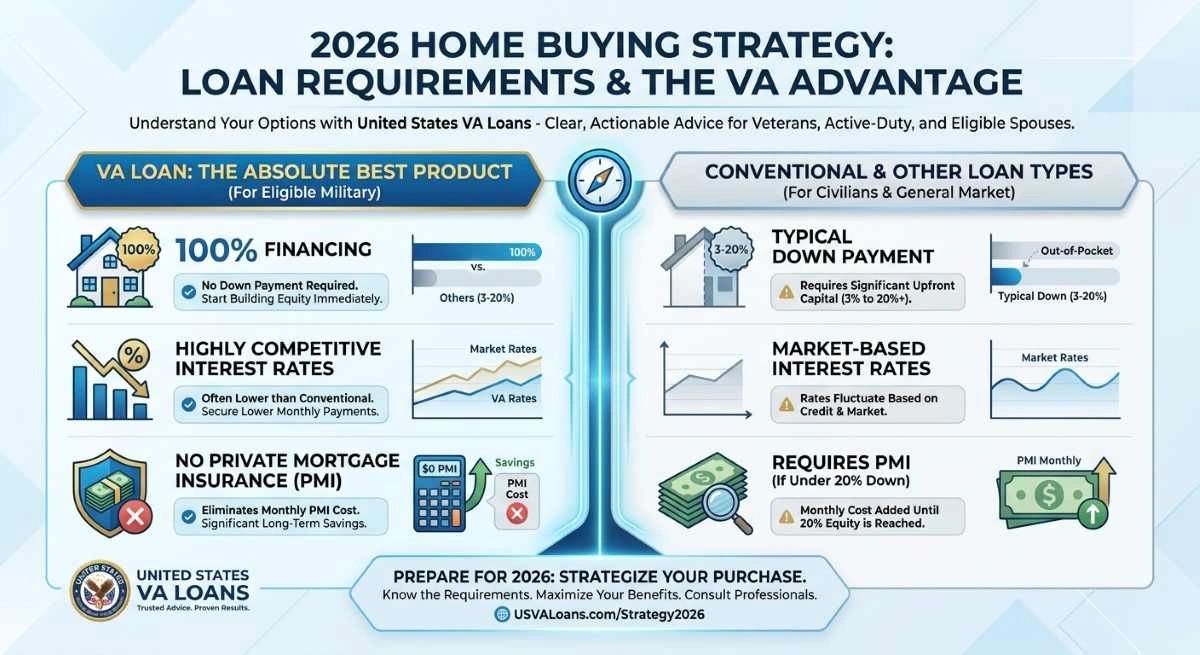

Ways to Save Your Property from Financial Risk
Table of Contents
Home loan loans are used to buy a home or to borrow money against the value of a home you already own. The size of the loanThe rate of interest and any associated pointsThe closing expenses of the loan, including the lender's feesThe Interest rate (APR)The type of rates of interest and whether it can alter (fixed or adjustable)The loan term, meaning for how long you need to pay back the loanDoes the loan have dangerous functions, such as a prepayment charge, a balloon clause, an interest-only feature, or negative amortization Lenders inform you how much you are certified to obtain that is, just how much they want to lend you.
Strategies to Prevent Foreclosure During 2026Just how much you qualify to borrow is different from how much you can manage to pay on a regular monthly basis, with the rest of your spending plan in mind. Lenders do not consider all your family and monetary situations. To understand just how much you can afford to pay back, you require to take a tough look at your family's income, costs, and priorities to see what fits easily within your budget.
You can get quotes from your local tax assessor, insurance coverage representative and lender. Knowing just how much you can easily pay each month also helps you approximate a sensible price variety for your new home.
the evaluated worth of a home. This is used in part to identify if residential or commercial property mortgage insurance (PMI) is required. the quantity a customer is obtaining versus the home. If the loan amount is above 80% of the appraisal then PMI is required up until the loan is paid off enough to where the Loan-to-value (LTV) is listed below is the priced quote APR a bank charges the borrower.
In basic discount rate points are a better worth if the customer plans to reside in the home for a prolonged duration of time & they expect interest rates to increase. If the buyer thinks rate of interest will fall or strategies on moving in a couple of years then points are a less engaging option.
Evaluating Current Home Relief Solutions
For your benefit we also.the variety of years the loan is arranged to be paid over. The 30-year fixed-rate loan is the most typical term in the United States, but as the economy has went through more frequent booms & busts this century it can make sense to buy a smaller home with a 15-year home loan.
Additional payments applied straight to the principal early in the loan term can conserve lots of years off the life of the is the local rate homeowner are charged to spend for various municipal expenses. Those who rent eventually pay this expense as part of their rent as it is reflected in their rental rate.
Property portals like Zillow, Trulia,, Redfin, & Movoto list current & historical real estate tax payments on numerous homes. If property tax is 20 or listed below the calculator treats it as an annual assessment portion based on the home's rate. If residential or commercial property tax is set above 20 the calculator presumes the quantity gone into is the annual evaluation quantity.
is just needed on standard mortgages if they have a Loan-to-value (LTV) above 80%. Some home buyers to use as part of their downpayment on the very first loan to help bypass PMI requirements. & have various down payment & loan insurance coverage requirements which are shown in their monthly payments. most house owner policies cover things like loss of usage, personal home within the home, house & structural damage & liability.
Historically flood insurance coverage has actually been heavily funded by the United States federal government, however in the recent home price healing some low lying locations in Florida have not recuperated as quickly as the rest of the market due in part to drastically increasing flood insurance coverage premiums. homeowner's association fees are common in apartments & other shared-property communities.

Review of New Loan Refinance Pathways
Understand that depending on develop quality can increase considerably 10 to 15 years after a structure is constructed, as any concerns with develop quality begin to emerge. Our website likewise releases a thorough glossary of industry-related terms.
Before you start searching for a home loan, it is essential to understand the different kinds of loans and choices you'll make when setting up your loan. Here's more about factors to consider when selecting a home loan. With a, the rate of interest released will stay the very same over the life of the loan, no matter what happens with rates in the market.
An starts with a set rates of interest for a set period (identified in your loan arrangement) and can alter or down depending on how rate of interest change in the market. Meaning, if you have a 10/1 ARM that suggests the interest rate is repaired for 10 years, and after that the new rates of interest changes when a year according to the loan arrangement.

Latest Posts
Refinance Advice to Reduce Payments in 2026

The Essential Guide to 2026 Home Loan Assistance
Benefits of Early Mortgage Relief in 2026