All Categories
Featured
He is a home mortgage expert with over 45 years of industry experience. Over his career, Harry has closed countless loans for satisfied borrowers and now provides his guidance and insights on FREEandCLEAR. Harry is a licensed mortgage professional (NMLS # 236752). More about Harry.
A lot of market conditions have improved especially for home mortgage and there may be more where that came from, depending on rates and location, ICE Home mortgage Technology's newest monthly analysis programs. Processing Content is at a two-year-plus high and rate drops have actually exposed millions to refinance rewards, with the share of mean income required for a normal home falling from 32% to 30%. The follow-up analysis of monthly information that the Intercontinental Exchange unit launched earlier provides loan providers several brand-new benchmarks, consisting of a method to size up re-financing potential customers and prepayment dangers in different rate circumstances.
A small drop like the brief dip listed below 6.25% in September temporarily included incentives for an extra half million customers for a total of 3.6 million. If rates fell even more to below 6.13%, another 1.4 million debtors or an overall of 5 million would have rewards. But it would take a drop to 2.5% to reach the maximum quantity of refinancing incentive, covering 37.3 million loans.
Managing Debt with Strategic Planning
Around a dozen of the 100 biggest markets have actually reached that point and most of them are in that area. Metropolitan locations that have not gained from a turnaround in price include Los Angeles, where the portion of mean income required is 62%. San Diego, Oxnard, and San Jose, California, likewise are markets where price strains exist, as are New York City and Miami.
The typical loan-to-value ratio for refis inched up at 80.1%. The rise in LTV "suggests borrowers with greater loan balances and raised LTVs may have been first in line for relief."Other current numbers reveal The business's discovered foreclosure sales have accelerated and other numbers have shown hints of issues in surrounding consumer financing sectors, however the most recent analysis of mortgage credit signs reveals enhancement."While typical credit rating for rate-and-term refinances was up to a more than two-year low of 689 in mid-August, it reached 722 in the week ending Sept.
The credit history of rate-locked purchase home loans topped 736, marking a six-year high in line. The typical debt-to-income ratio for a rate-locked purchase loan dipped to a two-and-a-half year low of 38.5%. The average 34.1% DTI for refinances was the most affordable considering that March 2022. DTIs still have not come back to the lower levels seen during and prior to the pandemic.
In a timely section of the report, given, IMT took a look at climate and home insurance data to assess how widespread the issue is. The cost savings from low-interest rates is getting watered down as rates move higher. The typical rate for 30-year fixed-rate home loan with conforming loan balances ($548,250 or less) increased to 3.36% from 3.28%, up 50 basis points given that the beginning of the year.
Strategic Mortgage Planning Advice for 2026March 16 rates at 3.36% = $1,544 January 1 rates at 2.86% = $1,449 Average 30-Yr Loan Balance: $548,350 or less"Mortgage rates have moved higher in tandem with Treasury yields, as the outlook for the U.S. economy continues to improve in the middle of the quicker vaccine rollout and states alleviating pandemic-related constraints," MBA Associate Vice President of Economic and Market Forecasting Joel Kan stated in a statement.
On an unadjusted basis, the index reduced 2% compared to the previous week. Home loan applications for re-financing a home reduced 5% from the previous week and were 13% lower compared to the exact same week a year back, according to the MBA's refinance Index. Conventional refinancing applications decreased 4.7% from the previous week while government refinancing applications decreased 6.5% from the previous week.
Still, property buyer need remains strong, with home loan applications to acquire a home increasing 3% last week from the previous week, according to the MBA's seasonally adjusted purchase index, marking the fourth straight week of gains. When unadjusted, the purchase index increased 3% compared to the previous week and was 26% higher than the very same week a year earlier."Purchase applications were strong over the week, driven both by homes looking for more home and younger households looking to go into homeownership," Kan added.

Latest Posts
Refinance Advice to Reduce Payments in 2026
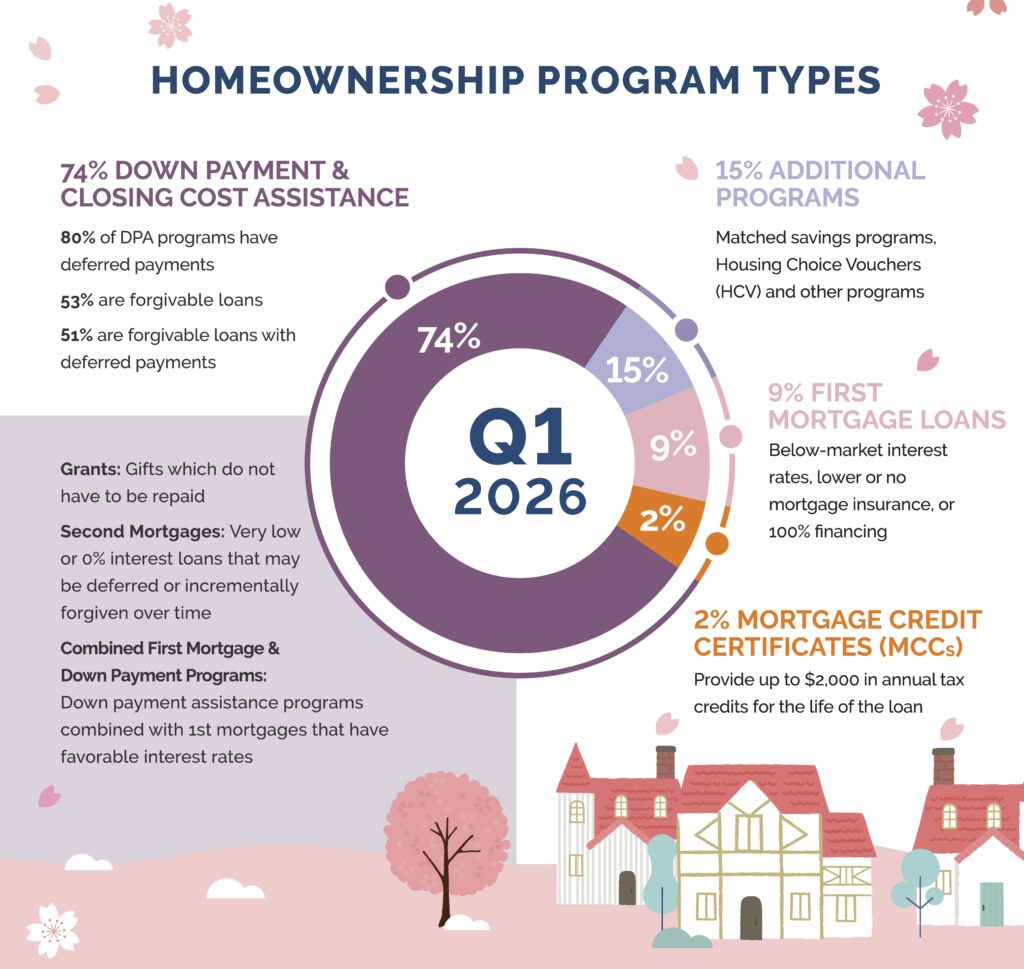
The Essential Guide to 2026 Home Loan Assistance
Benefits of Early Mortgage Relief in 2026